Have you ever wondered what happens in the magical seconds between clicking “apply for loan” on your finance app and getting a response, whether it’s a “congratulations, you’re approved!” or an “unfortunately, we couldn’t approve your request”? What used to be a days-long process involving stacks of paper, bank managers, and prolonged anxiety is now resolved in less time than it takes to make a cup of coffee. This speed isn’t magic; it’s the result of complex data engineering, artificial intelligence, and a new way of understanding human behavior—the pillars of modern financial technology (FinTech).
Forget the image of a scowling credit analyst hunched over your bank statements. In the FinTech universe, the credit decision is a verdict delivered by sophisticated algorithms that analyze hundreds, or even thousands, of data points about you. They build a digital mosaic of your financial life, far more detailed and dynamic than the traditional credit score. This article will open the black box of these apps and show you how they really decide whether or not you’re a good candidate for a loan.
🌐 The First Digital ‘Handshake’: The Data Collection You Don’t Even Notice
From the moment you download and open an app from a financial technology company, the evaluation process has already begun. This first contact is much more than a simple registration; it’s a meticulous collection of metadata and behavioral signals. The app isn’t just recording your name and ID number. It’s observing how you interact with the interface, the speed at which you type, whether you hesitate when filling out certain fields, and even your smartphone model and the stability of your internet connection. These elements, known as “behavioral biometrics,” help create an initial reliability filter and prevent fraud.
Consider the case of Carlos, a freelancer who needed a small amount of working capital. He filled out the application quickly and confidently on his personal phone, connected to his home Wi-Fi. In parallel, a fraudster trying to use stolen data might exhibit different behavior: copying and pasting information, using a suspicious VPN, or hesitating in personal data fields. The FinTech algorithm is trained to differentiate these patterns. It analyzes a range of information to build an initial risk profile before even looking at your finances. This data includes:
- Device data: Your device model, operating system, battery level, and phone uptime. A newer, well-maintained device can be a subtle indicator of stability.
- Connection data: Network type (Wi-Fi or mobile data), internet provider, and geolocation. Applications made from unusual locations or networks can raise a red flag.
- Navigation patterns: The time spent on each screen of the app, the order in which fields are completed, and the presence of excessive corrections in the form.
- App permissions: Access to your contact list or calendar (with your explicit permission, of course) can be used by some apps to verify the robustness of your social and professional network as an indicator of stability.
This initial layer of analysis is crucial. It not only optimizes the user experience, making the process smoother and faster, but also serves as a powerful security system. For the FinTech company, a user who navigates with confidence and provides information consistently is a strong indicator of legitimacy. It’s the first of many filters that define the path of your application, a sort of digital handshake where the first impression is, indeed, the one that gets logged on the company’s servers.
💡 Beyond the Credit Score: The Alternative Data Revolution
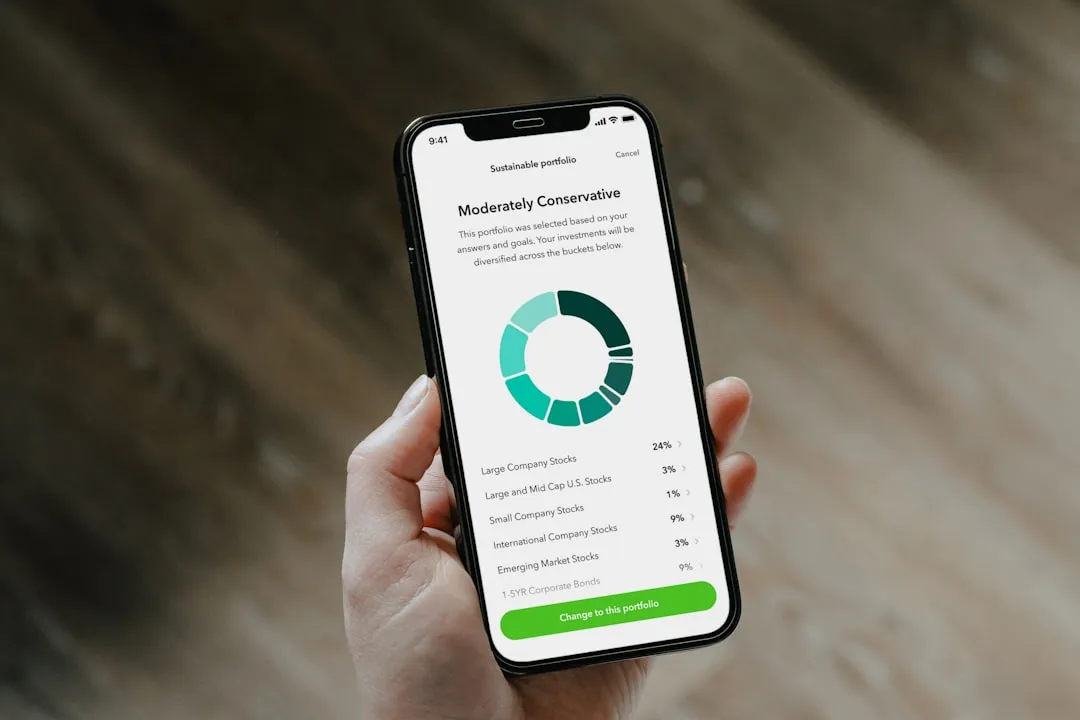
The traditional credit score (like those from Experian or TransUnion) was, for decades, the main pillar of risk analysis. It’s a good indicator of your financial past, but it has significant limitations. It doesn’t reflect an individual’s future potential and can unfairly penalize people with a short or nonexistent credit history, such as young people, freelancers, and immigrants. The great revolution of financial technology was precisely to look beyond this number, incorporating so-called “alternative data” to create a 360-degree view of the applicant. This movement not only makes decisions more accurate but is also a cornerstone of financial inclusion, as the World Bank points out, by allowing millions of people “invisible” to the traditional banking system to access credit.
This alternative data is a universe of information that, when connected, paints a portrait of your lifestyle, responsibility, and stability. Machine learning algorithms are designed to find correlations between this data and the probability of default. For example, a history of timely utility bill payments (electricity, water, internet) or rent can be as strong an indicator of financial responsibility as paying off a loan. A financial services technology company might analyze your online shopping behavior, how often you use ride-sharing or delivery apps, and even your educational background and professional history to infer your income potential and personal organization.
The difference between the traditional approach and the innovative FinTech approach is stark. While the old model is reactive and based on the past, the new model is predictive and looks to the future. A study by the Boston Consulting Group (BCG) highlights how artificial intelligence allows for unprecedented personalization in the lending process. This means the analysis goes beyond a simple “yes” or “no,” and can offer customized products for each risk profile. Here’s a direct comparison:
| Analysis Factor | Traditional Model | FinTech Model |
|---|---|---|
| Credit History | Primary focus. Past debts and credit bureau scores. | One of many factors. Combined with payment history for utility bills, rent, etc. |
| Proof of Income | Requires pay stubs, tax returns. Rigid for freelancers. | Analyzes bank statements via Open Banking, transactions in payment apps, and income from freelance work. |
| Behavioral Profile | Not considered or subjectively assessed by the manager. | Analyzes online shopping data, app usage, social media (with consent), and behavioral biometrics. |
| Future Potential | Ignored. Analysis is based solely on the past. | Considers educational background, professional field, and LinkedIn data to estimate income stability and growth. |
🧠 The Brains Behind the Decision: Artificial Intelligence and Machine Learning
When you submit a loan application on a financial technology app, it’s not a bank manager with a calculator analyzing your data. Behind the scenes, a much more complex digital brain is at work: Artificial Intelligence (AI) and Machine Learning (ML) algorithms. Unlike traditional credit models that rely on static rules (if score X and income Y, then approve Z), AI systems are dynamic and learn continuously.
Imagine the algorithm as a detective who has already investigated millions of loan cases. It doesn’t just look at your credit score; it searches for subtle patterns that humans couldn’t identify. AI cross-references thousands of data points to predict one single thing: the probability that you will pay back the loan. According to a Deloitte report on AI in banking, this technology allows for a much more granular and rapid risk assessment, transforming a process that took days into a decision of seconds.
Quick Case Study: The Case of the Digital Twins
Think of two brothers, Peter and Luke, both 30 years old, with the same income and an identical credit score of 720. At a traditional bank, their chances would be the same. For a fintech, however, it’s a different story. The algorithm notices that Peter has a history of consistent, small investment transactions in his connected account, while Luke makes frequent cash withdrawals from ATMs late at night and has several subscriptions to online betting services. Although both pay their bills on time, the AI identifies Peter’s behavior as lower risk, offering him a loan with lower interest rates. This is the precision that modern financial technology provides.
📱 Your Smartphone as a Financial Mirror: The Analysis of Alternative Data
The great revolution of fintechs lies in their ability to use “alternative data”—information that goes far beyond your credit report and bank statement. And the main source of this data is the device you’re using to read this article: your smartphone. With your permission, of course, apps can analyze a vast range of information to build a 360-degree financial profile about you.
This approach is especially powerful for including people without a traditional credit history in the financial system. Companies like Tala, which operates in emerging markets, have become giants of financial technology by using smartphone data to offer credit to millions of people “invisible” to banks. What do they analyze?
- 📜 In-App Behavioral Data: How long does it take you to fill out the form? Did you read the terms and conditions or just scroll to the end? Speed and attention to detail can be interpreted as indicators of responsibility.
- 📲 Device Information: Your phone’s model, its age, the battery percentage at the time of application, and even the number of contacts in your address book can be used as variables. A study from the University of Frankfurt found correlations between a phone’s battery level and financial decision-making.
- 📊 Transaction Patterns: Beyond looking at the balance, AI analyzes the frequency and nature of your transactions. Regular deposits (even if informal) can indicate a stable source of income, while multiple payment reversals can be a red flag.
- 🌍 Geolocation: The frequency with which you travel or the places you visit can, in some models, help corroborate information about your employment or lifestyle.
🎭 The Psychology of Credit: How Your Digital Habits Reveal Your Risk Profile
Going a step beyond raw data, the most advanced financial technology delves into psychometrics and behavioral economics. The way you interact with technology can reveal personality traits that are directly linked to your financial trustworthiness.
Sofia’s Story: Haste Makes Waste (and Denials)
Sofia needed a quick loan for an emergency. At 2 AM, she downloaded a fintech app and filled out the form hastily, making typos and entering information in all capital letters. The algorithm, trained to recognize patterns of stress and urgency, flagged her application as high-risk. It wasn’t about *what* she wrote, but *how* she wrote it. In contrast, a user who fills out the same form calmly and methodically during business hours is perceived as more organized and, therefore, less risky.
Even the type of email you use can influence the decision. A professional email address (e.g., firstname.lastname@email.com) tends to have a higher correlation with approvals than an informal one (e.g., kitty_2005@email.com). This isn’t prejudice; it’s the result of analyzing millions of data points that show users with more formal emails have historically had a lower default rate. The machine’s logic is cold and based purely on statistical correlations, as detailed by credit experts at Experian.
🚀 The Future is Now: How to Prepare for the New Era of Credit Analysis
The era when your credit history was a static document locked away is over. Today, your financial health is a living organism, constantly updated by every transaction, every digital interaction, and every online habit. This might sound intimidating, but it’s actually an unprecedented opportunity to take control of your financial destiny. Financial technology isn’t an enemy to be feared, but a tool to be mastered.
Instead of fighting the system, learn to use it to your advantage. Your digital life is your new financial resume. Take good care of it.
To successfully navigate this new landscape, you need to adopt a proactive stance. Here are practical steps to build a digital footprint that fintech algorithms will love:
- ✅ Cultivate Digital Financial Hygiene: Connect your primary bank accounts to fintech apps and maintain a positive and consistent cash flow. Pay bills and invoices through digital means and always on time. Algorithms value predictability.
- ✅ Build a History of Trust: Start small. Take out a microloan or a low-limit credit card offered by a fintech and pay it back flawlessly. Each successful payment is a vote of confidence that teaches the algorithm you’re a good payer.
- ✅ Be Mindful of Permissions: When installing a new financial technology app, read the permissions you grant. Understand what data you are sharing and be comfortable with that exchange.
- ✅ Demonstrate Stability: Avoid erratic digital behavior before applying for credit, such as uninstalling and reinstalling financial apps, frequently changing your phone number, or having long periods of inactivity in your accounts.
The power is now in your hands. By understanding how the technology works and managing your digital presence intelligently, you stop being a mere spectator and become the architect of your own credit approval.
Frequently Asked Questions
How does the loan approval process in a FinTech app differ from a traditional bank?
The main difference is in the speed and the data used. FinTech apps use algorithms and artificial intelligence to analyze thousands of data points in minutes, including non-traditional sources. Traditional banks rely more on conventional credit histories and manual processes, which can take days. The FinTech decision is almost instantaneous, based on a much broader financial profile than just your credit score, making the process faster and often more inclusive.
What kind of “alternative data” do FinTech apps analyze?
Beyond your credit score, they analyze data such as your bank transaction history (to understand cash flow and spending habits), utility bill payments (electricity, water, internet), information about your education and career, and even your online shopping habits. The goal is to create a 360-degree view of your financial health, rewarding financial responsibility that doesn’t appear on traditional credit reports and assessing your true ability to repay.
Does having a low credit score mean I will be automatically rejected by a FinTech?
Not necessarily. While a good score helps, FinTechs are known for giving more weight to other factors. For example, if you have a stable and consistent income stream visible in your connected bank account, it can offset a lower score. They evaluate your current ability to pay, not just your past credit history. Therefore, a low score isn’t an automatic barrier as it might be at many traditional banks, opening doors for more people.
My application was denied. What can I do to increase my chances next time?
First, check your credit report for errors. Then, focus on demonstrating financial stability. Connect your main bank account to the app so the algorithm can see your income and expenses. Try to pay down small outstanding debts and avoid making multiple credit applications in a short period, as this can negatively impact your score. Maintaining a positive balance and paying bills on time are also crucial factors that algorithms value for building a trustworthy profile.
Is it safe to share so much financial data with a FinTech app?
Yes, as long as you choose apps from reputable companies. Regulated FinTechs use advanced security technologies, such as end-to-end encryption and multi-factor authentication, to protect your data. They also connect to your banks through secure APIs (Open Banking), which allow for controlled information sharing without exposing your bank passwords. Always check the app’s reputation and its privacy policies before using it.